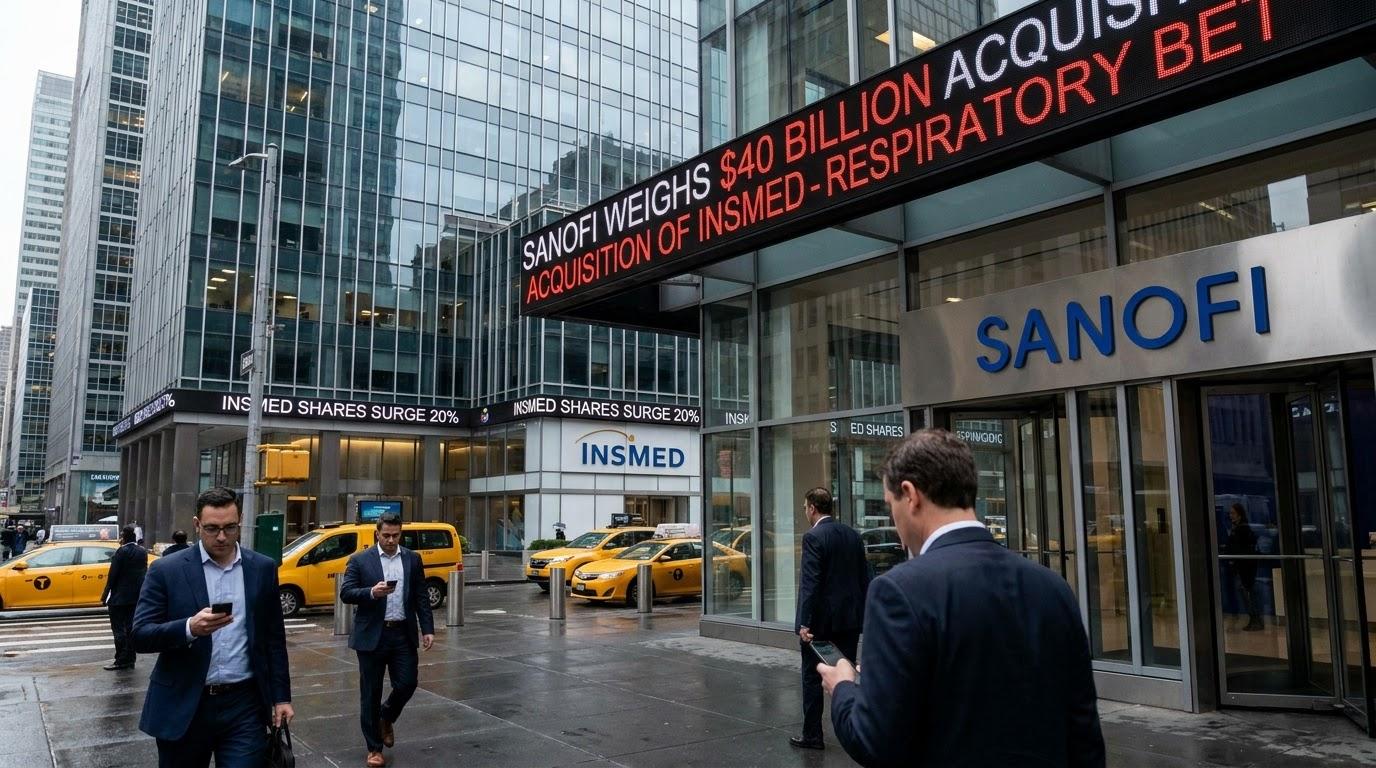
Insmed shares jumped more than 20% on Thursday after Bloomberg reported that Sanofi is weighing an acquisition of the company, citing people familiar with the matter. Some analysts are estimating a potential transaction at around $40 billion, a size that BMO Capital Markets said could make it the largest deal of the year if completed.
The market reaction was immediate. Insmed closed trading at $144 per share, up from $120 the previous day. BioSpace noted that $144 multiplied by around 219 million shares implies a value close to $31.5 billion, while Bloomberg placed Insmed at around $26.6 billion. Neither company commented to Bloomberg, and BMO said discussions likely remain ongoing, with other potential bidders still able to emerge.
The strategic fit
BMO called the potential combination a "clear strategic fit," arguing that it would add "Insmed’s differentiated respiratory growth engine to Sanofi’s existing commercial infrastructure in the therapeutics category." William Blair also said a deal particularly makes sense in light of Sanofi's commercial push into COPD after Dupixent's approval for chronic obstructive pulmonary disease in September 2024.
Insmed brings a concentrated pulmonary portfolio. The company markets Brinsupri, approved in August 2025 for patients 12 years and older with non-cystic fibrosis bronchiectasis, and Arikayce, an antibiotic for hard-to-treat mycobacterium avium complex lung disease. Brinsupri was the first treatment for bronchiectasis to reach the U.S. market.
The development story is broader than the current commercial base. Guggenheim estimated peak sales of about $15 billion across Brinsupri, Arikayce and late-stage candidate treprostinil palmitil inhalation powder, or TPIP. TPIP is in Phase 3 for pulmonary hypertension associated with interstitial lung disease and pulmonary arterial hypertension, and in Phase 2 for idiopathic pulmonary fibrosis.
The financing question
The main constraint in the reporting is not strategic logic but balance-sheet capacity. William Blair said a big question is whether Sanofi can truly afford an acquisition in the $40 billion range with current net debt of about €12 billion, or $13.2 billion as cited in the report.
That has pushed investors toward structure as much as rationale. William Blair noted speculation that Insmed's assets could be added to Sanofi's joint venture with Regeneron to provide additional capital to reach necessary valuations. Sanofi also paid Regeneron $1 billion upfront in early October to continue the search for a successor to Dupixent, which loses patent protection in 2031.
Sanofi management had already signaled appetite for larger business development. On the French pharma's third-quarter call last month, CEO Belén Garijo said the company plans to use its "robust cash flow generation to fund business development and M&A transactions," particularly later-stage or commercial opportunities. CFO François Roger added that a strong balance sheet and low leverage allow access to external financing for the next set of growth drivers.
If Sanofi proceeds, the signal is straightforward: large-cap buyers still appear willing to pay up for commercial or near-commercial respiratory assets that can slot into existing infrastructure. For Sanofi, an Insmed deal would not be a platform expansion so much as a concentrated attempt to deepen a therapeutic category where it already has momentum.