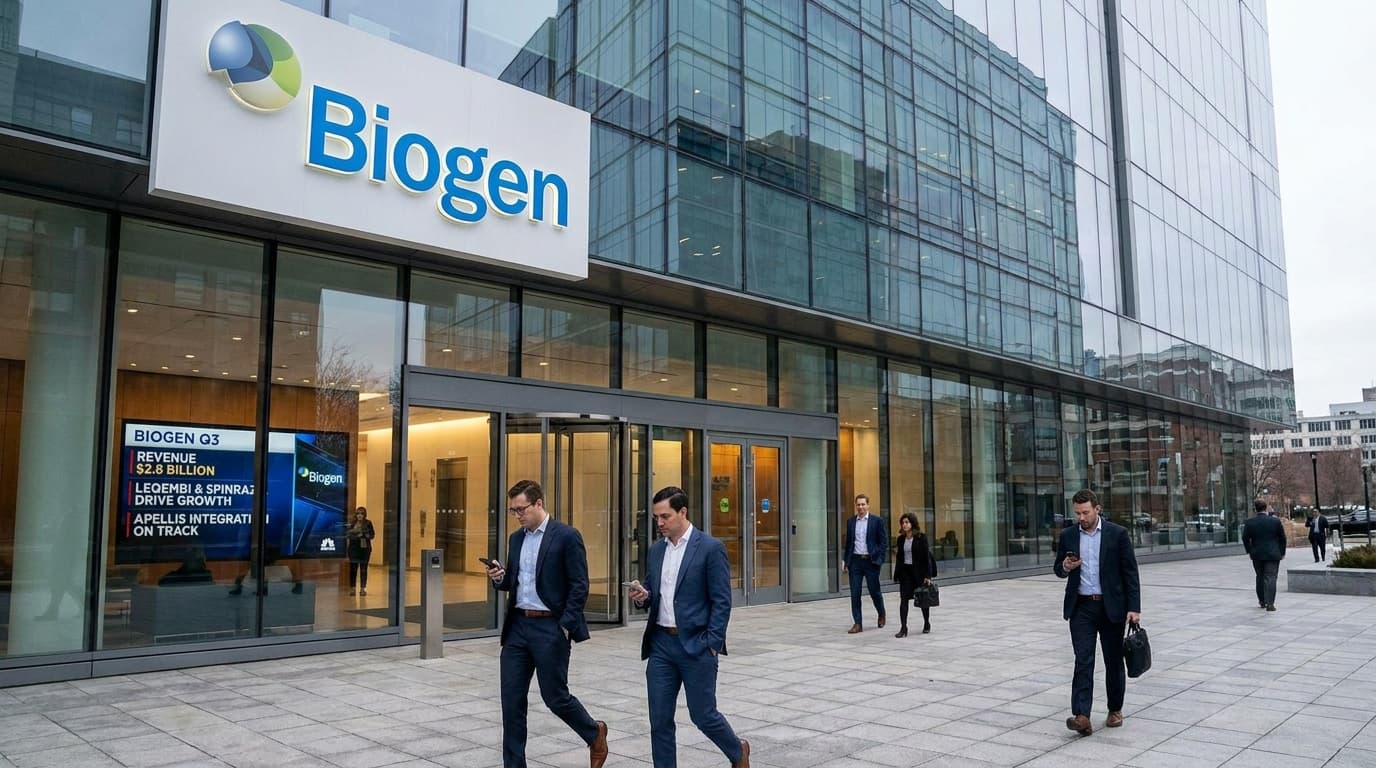
Biogen said it has returned to growth, reporting $2.8 billion in third-quarter revenue for its third straight quarter of top-line expansion. The quarter was driven by rising sales of Alzheimer’s therapy Leqembi, spinal muscular atrophy drug Spinraza and the first full earnings contribution from products gained in the company’s $5.6 billion acquisition of Apellis Pharmaceuticals in March.
Management’s message was that Biogen’s base business is no longer dependent on another large transaction to grow. On the earnings call, CEO Chris Viehbacher said that after the Apellis acquisition, the company now thinks it can grow even without the pipeline, and then add launches from late-stage assets on top of that base as data arrive.
The commercial picture
Biogen’s growth portfolio generated $1.26 billion in the quarter, up 49% year over year, according to the company’s earnings release cited by BioSpace. Spinraza contributed $461 million, which Biogen attributed to accelerated conversions to a high-dose regimen that exceeded company expectations in all markets. Leqembi added $202 million, up 67% year over year, including $107 million in U.S. sales.
Products from Apellis also helped. Syfovre and Empaveli combined for $243 million in quarterly sales, compared with consensus of $216.8 million, according to the BioSpace report. Truist Securities described the quarter as solid and said it reinforced confidence in execution and early Apellis integration.
Biogen slightly raised the lower end of its guidance to $12.20-$13 from $12-$13 previously. BioSpace also reported that Jefferies expects full-year revenue between $10.19 billion and $10.58 billion. Earnings per share landed at $2.62, ahead of the $2.14 analysts had been expecting, although acquired in-process research and development charges brought that down to a 14-cent loss when adjusted.
The signal for investors is that the growth debate is shifting. Biogen spent years trying to prove it could stabilize and then expand beyond legacy declines. With three quarters of revenue growth now in hand, the next question is less whether the base business can hold and more whether pipeline readouts can turn that recovery into a broader product cycle.
The road here
Viehbacher said Biogen has changed substantially in recent years. The company has expanded beyond a model centered on neurologists and now has commercial teams working with nephrologists, dermatologists, retina specialists and rheumatologists across the portfolio. That diversification has been accelerated by acquisitions over the past three years, with Apellis representing the latest-stage and most immediately accretive addition.
Even so, Viehbacher made clear that he does not prefer repeating that kind of late-stage deal. He said he has long disliked buying assets in later stages because a fair amount of risk still remains, and described discovery through Phase 1b assets that fit existing franchises as Biogen’s “sweet spot.” He also said the company has become more opportunistic than intentional about deals and wants to avoid overextending itself while it digests recent change.
That stance matters because it reframes M&A as optional rather than necessary. A company that believes its core business is growing can be more selective, especially when management is concerned about distraction from integrating new therapeutic areas and commercial channels.
What to watch
The main catalysts now sit in the late-stage pipeline. Biogen highlighted litifilimab in two forms of lupus, felzartamab in antibody-mediated rejection and zorevunersen for Dravet syndrome as key programs. Registrational readouts for litifilimab are due across the next four quarters, with two Phase 3 systemic lupus erythematosus readouts expected by the end of this year and a late-stage cutaneous lupus erythematosus readout in the first half of 2027.
Those data are likely to determine whether Biogen’s current growth streak becomes a bridge to a more durable expansion story. Truist said clinical catalysts should dominate Biogen shares over the next approximately 12 to 14 months, a view that fits management’s own effort to place future launches, rather than another major acquisition, at the center of the company’s next phase.